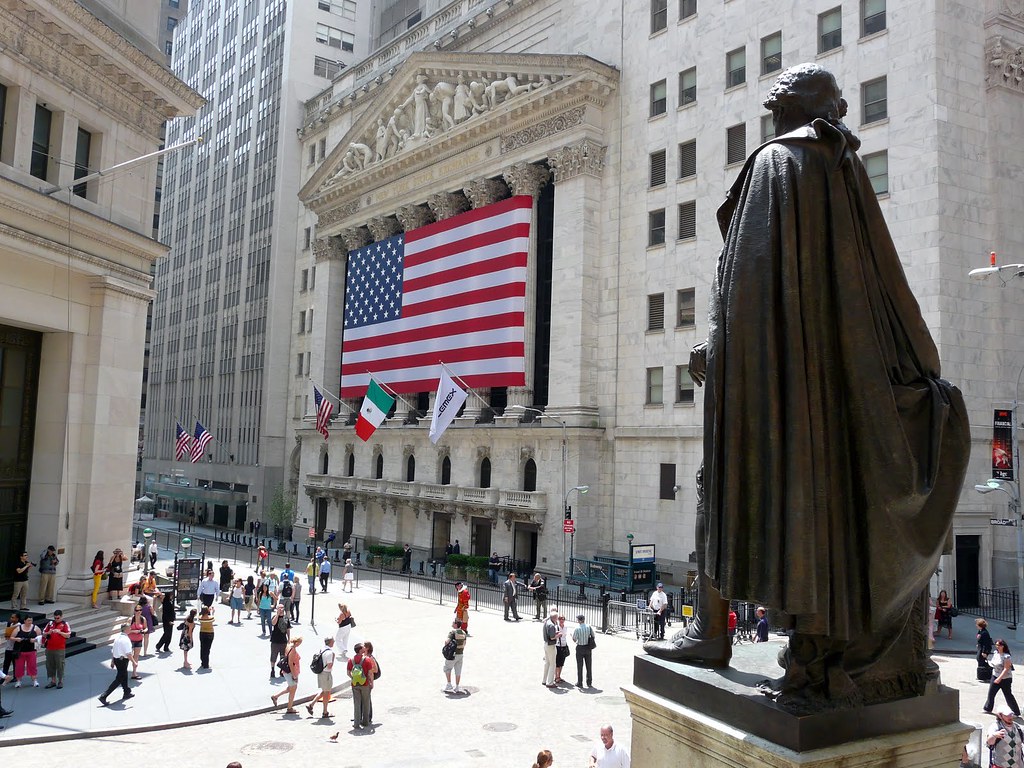
America’s stock market is approaching the fourth anniversary of a remarkable bull run, powered largely by unprecedented investment in artificial intelligence and the infrastructure needed to support it. Since bottoming out on October 12, 2022, the S&P 500 has climbed approximately 117%, with technology giants leading an expansion that has generated trillions of dollars in market value. Corporate earnings growth, massive data-center construction, and rising demand for advanced semiconductors have helped sustain investor confidence despite inflationary pressures and economic uncertainty. However, the rally’s increasing dependence on a handful of technology companies, combined with rising Treasury yields and tighter monetary policy, raises questions about its long-term durability. As Wall Street celebrates nearly four years of gains, investors face a fundamental question: whether artificial intelligence can deliver enough measurable economic productivity and profitability to justify the extraordinary valuations attached to its biggest beneficiaries.
Key Takeaways
• AI Powers Historic Gains: The S&P 500 has risen approximately 117% since October 2022, propelled by artificial intelligence investment, corporate earnings, and technology-sector expansion.
• Market Concentration Raises Concerns: The ten largest companies account for roughly 40% of the S&P 500, leaving investors increasingly exposed to the performance of a relatively small group of technology giants.
• Economic Headwinds Threaten Momentum: Elevated Treasury yields, Federal Reserve interest-rate increases, and uncertainty surrounding AI investment returns could challenge the market’s continued advance.
In-Depth
Wall Street’s extraordinary bull market is approaching its fourth anniversary, demonstrating the enormous financial influence of artificial intelligence on America’s economy. Since October 2022, the S&P 500 has advanced approximately 117%, supported by aggressive corporate investment, expanding profits, and widespread expectations that AI will fundamentally transform productivity.
Technology companies have driven much of that expansion. Nvidia, Microsoft, Alphabet, and other industry leaders have benefited from extraordinary demand for computing infrastructure, semiconductors, and data centers. Their investments have created opportunities throughout the technology supply chain while helping sustain economic growth despite persistent inflation and higher borrowing costs.
Yet the market’s impressive performance conceals a growing vulnerability. The ten largest companies now represent approximately 40% of the S&P 500, concentrating investor exposure in businesses whose valuations depend heavily on continued AI expansion. Such concentration leaves retirement accounts and investment portfolios vulnerable to sharp corrections if anticipated profits fail to materialize.
Higher Treasury yields present another challenge. As government bonds offer increasingly attractive returns, investors may reconsider paying elevated prices for equities, particularly technology companies whose valuations depend on expectations of future earnings.
Nevertheless, the rally illustrates the capacity of private enterprise, technological innovation, and capital investment to generate substantial wealth. Artificial intelligence could produce lasting productivity improvements across manufacturing, medicine, transportation, and countless other industries.
The critical distinction is between genuine economic advancement and speculative enthusiasm. Sustaining this bull market will require measurable profitability, broader participation across economic sectors, and financial discipline. Innovation creates opportunity, but market confidence ultimately must rest on results rather than promises.